When cooler weather settles over the Corridor and everyone heads indoors, you notice all the little things you forgot about over the summer. Like your drafty living room windows and the peeling trim in your guest bathroom.
Whether you’re staying put and want to love the space you spend time in, or you’re thinking about listing your home in the spring, home improvement projects are top of mind this time of year.
If you’ve been considering a home equity line of credit (HELOC) for home improvement and wondering how it works, keep reading. While we leave the financial details to our local banks and credit unions, we did ask our agents which upgrades are worth your time and money.
But first, let’s review some of the basics of how lenders structure a HELOC and why it works so well for home improvements.
What Is a HELOC and How Does It Work?
A HELOC lets you borrow against your home equity, which is the gap between what your home is worth today and what you still owe on your mortgage.
Instead of giving you a lump sum like a standard loan, a HELOC works a lot like a credit card. You’re approved for a maximum amount, but you only draw what you need, when you need it, and you only pay interest on what you spend.
Most HELOCs have two phases:
- The Draw Period (5 to 10 years): You can borrow, pay back, and borrow again as your project unfolds. During this time, many lenders only require you to pay the interest on what you’ve used.
- The Repayment Period (often up to 20 years): Once the draw window closes, you can no longer pull money out. Your monthly payments cover both principal and interest, which means your bill will likely go up.
HELOC rates are usually variable, so your rate and your monthly payment can change with the broader market. As for how much you can access, local banks and credit unions typically let you borrow up to 80–85% of your home’s total value, minus your remaining mortgage balance.
Is a HELOC a Good Idea for Home Improvement?
The pay-as-you-go structure of a HELOC is a huge plus because it gives you flexibility. Renovations rarely happen in one clean transaction—contractors bill in stages, and if you’re remodeling an older home, you might find surprises behind the drywall.
With a HELOC, you can pull money out as invoices arrive, rather than borrowing a big lump sum upfront and paying interest on cash that’s sitting in your checking account.
It’s also satisfying to put that money back into the home you’re building equity in. And if you’re using the money for major improvements, the interest might even be tax-deductible. Be sure to ask your CPA or tax professional about the specifics (more on that later).
Since your house serves as collateral, a HELOC makes the most sense when you’re investing in projects that add lasting value to your home.
Staying or Selling? What Corridor REALTORS® Say Is Worth Completing
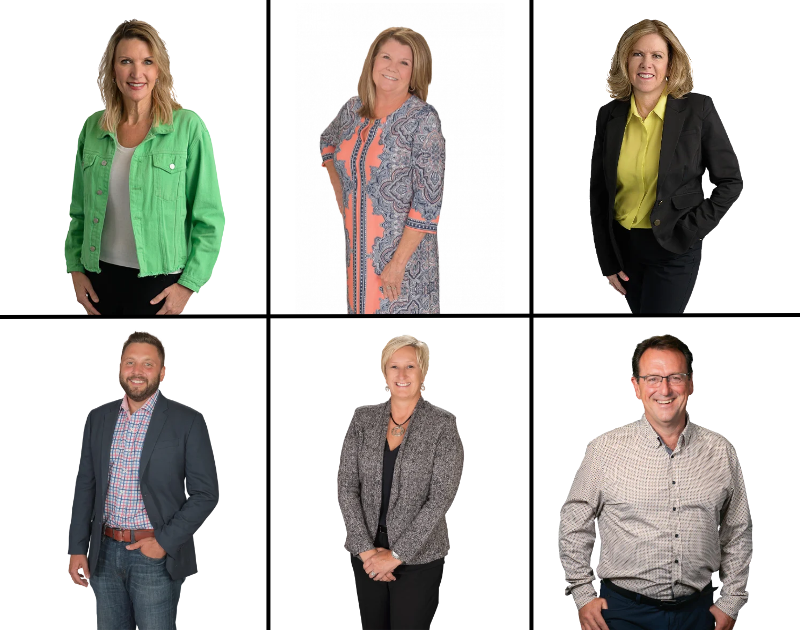
We asked six Urban Acres agents about the home updates that make the biggest impact. The consensus? The projects that catch a buyer’s eye are almost always the same improvements you’ll wish you’d made sooner.
What Buyers Notice First
Nearly every agent listed the kitchen as a top priority, with bathrooms coming in a close second.
REALTORS® Rob McCain and Jan Crosby
Jan Crosby highlighted kitchen cabinets as a major focal point, while Rob McCain noted that fresh cosmetic updates are usually what make buyers stop and take notice the moment they walk through the door.
If You’re Staying
REALTOR® Ross Nusser
“Flooring, kitchens, and baths,” says Ross Nusser, recapping the projects clients most often wish they’d tackled earlier. “If you’re going to pay for it, you might as well enjoy it.”
REALTOR® Tricia Van Roekel
Flooring came up repeatedly among our team. When asked what updates homeowners wish they’d done sooner, Tricia Van Roekel named paint, flooring, and decluttering.
Rob noted that people often delay replacing their floors because they think floor coverings are more expensive than they really are.
REALTOR® Cindy Clark
Cindy Clark sees a different kind of regret: homeowners wishing they’d replaced their roof and gutters years earlier. While replacing an aging roof offers daily peace of mind if you stay in the home, Cindy notes it’s also a project where sellers routinely overspend before listing and rarely recover the full cost at closing.
If you plan to stay put for a while, improvements like new windows or added insulation make Iowa winters more comfortable. Rob points out that window replacements are another area where sellers rarely get a full return at closing. Windows are a far better investment if you’re sticking around to enjoy the cozy results.
Thinking even longer term? Our post on Iowa’s ADU law covers another way to expand your space.
If You’re Listing in the Spring
If you’re prioritizing high-impact updates, stick to the basics: kitchens, bathrooms, and flooring. These are the areas buyers notice and appreciate most when walking through a home.
REALTOR® Karen Peterson
When it comes to the bigger, costlier projects, our agents recommend treading lightly. Karen Peterson notes that finishing lower-level storage spaces just to add extra square footage is where sellers often spend more than buyers are willing to pay for.
Jan mentioned solar panel installations as a feature that rarely yields a direct return at resale.
Landscaping is more of a gray area. Ross and Tricia both caution that grand, sprawling outdoor projects often turn into overspends.
On the flip side, Jan sees value in using a HELOC for targeted curb appeal improvements or critical foundation repairs.
Low-cost efforts, like fresh mulch, tidied garden beds, and neatly trimmed shrubs, can go a long way in listing photos. But investing in a brand-new retaining wall or elaborate patio is a riskier call if you plan on moving in a few months.
Before taking out a loan or committing to a major contractor bid, have an Urban Acres agent walk through your home. We can tell you what buyers in your neighborhood expect and which projects are most likely to pay off.
If you’d rather skip the hassle of remodeling altogether, check out our guides on home staging costs and how to sell a home as-is.
A quick note for future sellers: If you sell a home with an open HELOC balance, it gets paid off at closing from your sale proceeds, alongside your mortgage.
Ask your bank or credit union about early closure terms, as some lenders charge a fee if you close out the line within the first few years.
HELOC vs. Other Ways to Pay for Home Improvements
A HELOC is just one way to fund your project. Here’s how the most common options compare:
HELOC
How you get the money: Draw as needed
Rate: Usually variable
Good fit for: Phased projects or uncertain costs
Home Equity Loan
How you get the money: One lump sum
Rate: Usually fixed
Good fit for: A single project with a set price
Personal Loan
How you get the money: One lump sum
Rate: Usually fixed, often higher
Good fit for: Smaller projects, without using your home as collateral
Cash-Out Refinance
How you get the money: Lump sum through a new mortgage
Rate: Fixed or adjustable
Good fit for: Larger projects when today’s rates are near or below your current rate
A cash-out refinance replaces your current mortgage entirely, so it’s hard to justify if you locked in a low rate when you bought your home.
Is HELOC Interest Tax Deductible?
Sometimes, but there are specific rules. Under federal law, HELOC interest is generally deductible only if you itemize and use the funds to buy, build, or substantially improve the home securing the loan. These requirements—along with the $750,000 overall mortgage debt limit ($375,000 if married filing separately)—were made permanent by the 2025 federal tax law.
Tapping a HELOC for a kitchen remodel may qualify, but using it to clear credit card debt or buy a new car won’t.
Before You Borrow
- Get contractor bids first. Know your project scope and request 10–20% above the estimate so you have a buffer for unexpected costs without needing to reapply.
- Plan for the payment jump. During the initial draw period, you may only need to pay interest. Add up what your combined principal + interest payment will be once the repayment period begins, and factor in potential interest rate increases to ensure it fits your long-term budget.
- Apply early. HELOC typically takes 2 to 6 weeks from application to funding. If you want work finished before winter or ahead of a spring listing, start the paperwork well in advance.
Do You Have to Use a HELOC for Home Improvements?
No, you don’t have to use a HELOC exclusively for home improvements. Once approved, you can use the funds for virtually any purpose, including debt consolidation, major purchases, medical bills, or education expenses.
Home improvements are one of the most common uses, and they’re the only one that can make your interest tax-deductible.
Planning Fall Projects
Fall is a great time to start planning home projects, whether you’re settling in to enjoy your space for a few more seasons or getting a jump on a spring listing.
If you aren’t sure which updates make the most sense for your neighborhood and price point, an Urban Acres agent can share what buyers are looking for in today’s market.
And when you’re ready to look at financing options and current rates, reach out to a trusted local bank or credit union. We’re always happy to make a recommendation if you need one!